FEDERAL SCHOLARSHIP TAX CREDIT

A New Way For Families to Access Christian Education
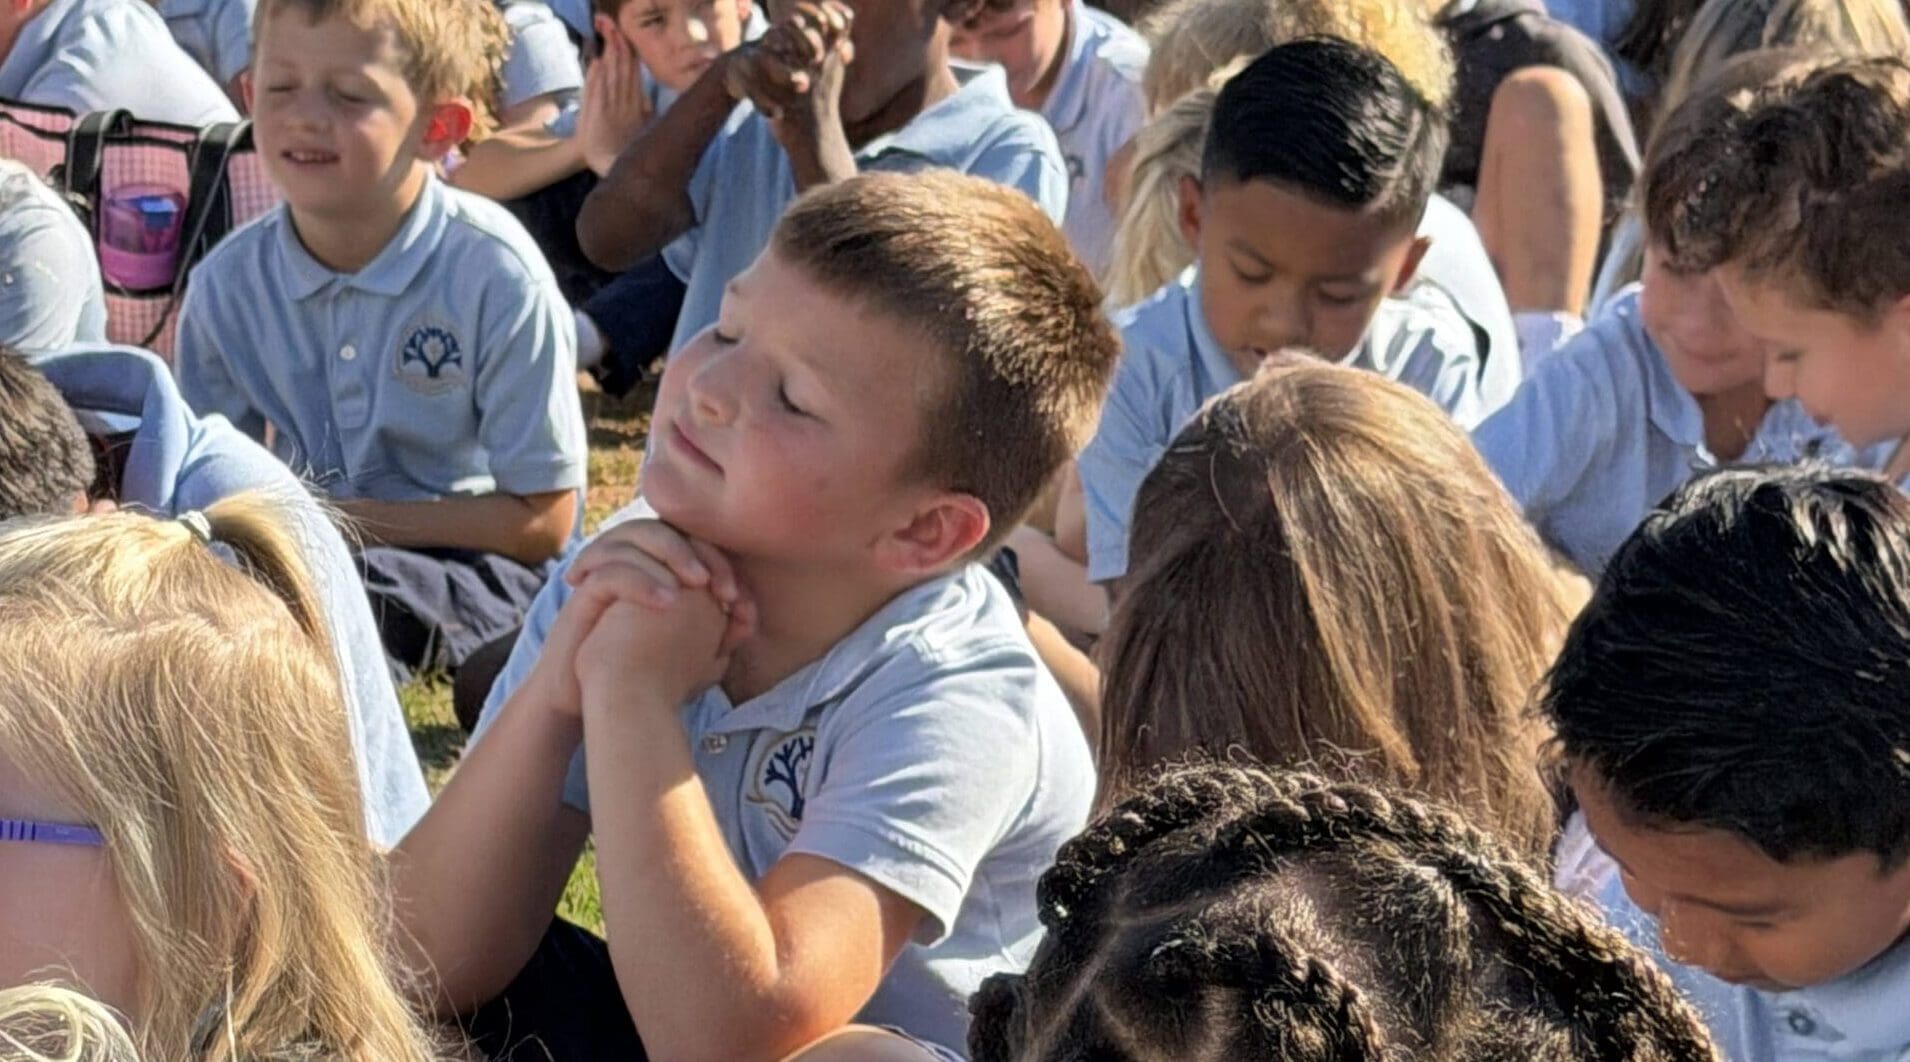
Learn how a qualifying scholarship gift could reduce your federal income tax and help more families choose a Christian education.

We know how much it means to find a school where your child is known, encouraged, and growing in faith. Beginning in 2027, a new giving opportunity could help more families find that home at Oakbrook.

Here’s how you can help: make a qualifying cash gift to an approved nonprofit that awards student scholarships, called a Scholarship Granting Organization (SGO). Then claim a credit on your federal income tax return. If you qualify for the full credit, a $1,700 gift reduces your federal income tax by $1,700, or $3,400 combined for married couples filing jointly when each spouse contributes. Your tax adviser can help you determine how much credit you can use.

We’re working to confirm Oakbrook’s scholarship partner and will share how to give once those details are ready. In the meantime, we’d love to hear from you, answer your questions, and help you consider how your gift could welcome another family into our Oakbrook community.


How your gift can help a student:
1. Check your eligibility

Ask your tax adviser about your available federal income tax liability and the credit rules. Confirm that the SGO appears on the applicable approved list for the contribution year.

2. Make a qualifying gift

Beginning January 1, 2027, contribute cash to an approved SGO. Once Oakbrook confirms a partner and giving route, follow its instructions for supporting eligible Oakbrook students. School designation depends on the SGO’s policies.

3. Save your documentation

Keep the SGO’s acknowledgement and required contribution records. Follow its instructions, including how each spouse’s contribution is recorded if filing jointly.

4. Claim the tax credit

Claim the eligible credit on your federal income tax return for the year of the gift. For a calendar-year taxpayer, a 2027 gift generally goes on the 2027 return filed in 2028. The SGO separately verifies student eligibility and awards scholarships.

Questions You May Be Asking:
The IRS calls it the Federal Scholarship Tax Credit (FSTC), under Internal Revenue Code Section 25F. You may also hear Education Freedom Tax Credit. These names refer to the same federal credit.

Federal law sets an annual limit of $1,700 per individual taxpayer. October 2026 proposed regulations describe a combined credit of up to $3,400 for married couples filing jointly when each spouse makes qualifying contributions. Confirm contribution documentation and your usable credit with your tax adviser. The IRS says taxpayers may rely on the proposed regulations for qualifying contributions beginning January 1, 2027.

Yes. IRS guidance states that donors may contribute to an eligible SGO regardless of their state of residence, including when their home state does not participate. The SGO must qualify in a participating state. Once Oakbrook’s partner and giving route are confirmed, friends and relatives across the country can consider supporting scholarships through that route.

You make a qualifying donation with your own funds and then claim a federal income tax credit. It is not an automatic transfer from the IRS to Oakbrook. A usable credit can reduce your federal income tax by the amount of the qualifying gift, within the annual limit. Continue meeting your tax payment obligations and ask your adviser before changing withholding or estimated payments.

No. A credit reduces tax dollar for dollar; a deduction reduces taxable income. You cannot claim a federal charitable deduction for the same contribution for which this credit is allowed. A state tax credit for the contribution can also affect the federal credit.

This credit requires a qualifying cash contribution to an approved SGO. A direct gift to Oakbrook, a tuition payment, or an event purchase does not automatically qualify. Stock and grants from a donor-advised fund are not the individual’s qualifying cash contribution for this credit.

No. Federal law prohibits earmarking contributions for a particular student. A contribution cannot be directed to your own child’s tuition or exchanged for a guaranteed scholarship. The SGO determines scholarship awards under its eligibility and award rules.

Federal eligibility generally includes students eligible to enroll in public elementary or secondary school whose prior-year household income does not exceed 300% of area median gross income, adjusted for family size. The SGO verifies eligibility. Meeting an income limit does not guarantee an award. Oakbrook’s K3 and K4 programs should not be assumed eligible under this K-12 program.

The gift goes to the SGO, which administers the scholarships and has operating costs. Any school designation and distribution rules depend on the confirmed partner’s policies. Scholarship support helps eligible students attend Oakbrook; it is not automatically unrestricted funding for the school.

No. ESTF is South Carolina’s scholarship program. This new federal program encourages donations to approved nonprofit organizations that award student scholarships.

The scholarships may be “stacked,” or used together, if your family qualifies for both programs. For example, an SGO scholarship could help cover eligible tuition costs remaining after ESTF funds are applied, subject to both programs’ rules.

Each program has its own application and eligibility requirements. We’ll be happy to help your family understand how these opportunities could work together once Oakbrook’s SGO partner and award policies are confirmed.

The Section 25F credit applies to eligible individual U.S. citizens or residents. Business owners, employees, church members, grandparents, alumni, and friends can learn about participating as individuals. A corporation or church does not receive this individual credit simply by making a donation. Organizations can help share the information.

The federal credit begins in 2027. A gift made in 2026 does not qualify for this new credit. For now, learn about the program, share this information, and contact Oakbrook for updates. Confirm approval and the giving instructions before making a 2027 gift.

share this with someone you know…

You do not have to live in South Carolina—or have a child at Oakbrook—to participate. Grandparents, relatives, alumni, and friends in other states can make a qualifying donation and claim the federal tax credit if they meet the requirements.

Even if their home state does not participate in the program, they can give to an approved Scholarship Granting Organization (SGO) in a state that does. What matters is that the scholarship organization qualifies in a participating state, rather than where the donor lives.

Once Oakbrook confirms its scholarship partner and giving instructions, we will share how donors can support scholarships for eligible Oakbrook students. We invite you to pass that information along to people who care about your family, our school, or Christian education. Your connection could help another family discover Oakbrook.


We’re here to help.

We will update this page as this program develops. For more information, please reach out!

Contact

Head of School Andy Bell at andy.bell@oakbrookprep.org or Admissions Director Amanda Ledbetter at amanda.ledbetter@oakbrookprep.org or at (864) 587-2060

Additional Resources:

IRS: Federal Scholarship Tax Credit and participating states

IRS: October 1, 2026 implementation announcement

Proposed regulations: Federal Register, October 2, 2026

Federal law: Internal Revenue Code Section 25F

This page is for educational information only, not tax, legal, or financial advice. Consult your professional adviser before making giving or tax decisions.